Retail Electricity Market overview and industry significance
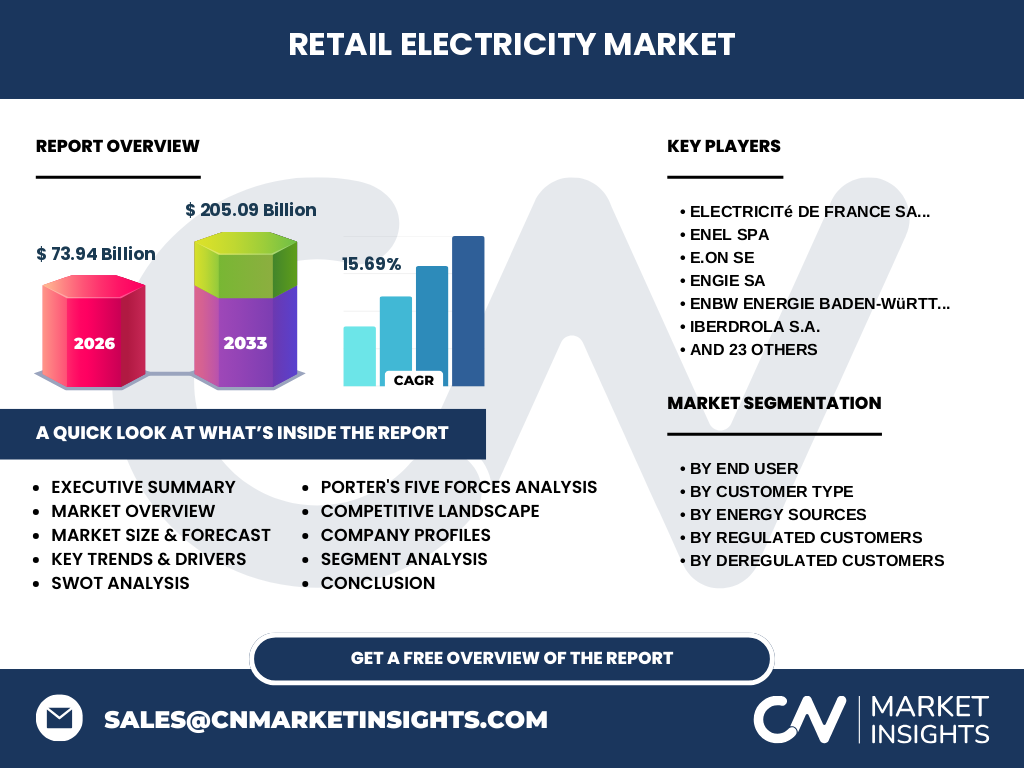
Our analysis indicates that the Retail Electricity Market market size stands at $73.94 Billion in 2026. This sector governs the final delivery, pricing, and metering of power to end-users, acting as the critical revenue realization bridge between wholesale generation grids and consumers.
Key market drivers, restraints, challenges, and opportunities shaping Retail Electricity Market
Growth is heavily propelled by smart meter deployments and decarbonization mandates. However, volatile wholesale fuel costs and strict regulatory price caps create margin compression. Opportunities lie in dynamic retail tariffs and virtual power plant integration.
The Shift Toward Decentralized Renewable Retail Offerings
Industry trends reveal a rapid consumer migration toward localized green tariffs. Major utilities like E.ON SE and Iberdrola S.A. are pivoting rapidly to capture eco-conscious residential demand through tailored zero-carbon supply contracts.
COVID-19 impact analysis and recovery trajectory
The pandemic drastically altered load profiles, shifting consumption from commercial hubs to residential sectors. The subsequent recovery features robust digital billing adoption and heightened focus on grid resilience, anchoring the sector's strong multi-year rebound.
Competitive benchmarking and strategic market dynamics
The competitive landscape features dominant players such as Electricité de France SA (EDF), Enel SpA, and Engie SA. Market concentration varies significantly between monopolistic regulated regions and highly competitive deregulated retail jurisdictions.
Executive summary of key findings
Our research confirms the Retail Electricity Market industry trends point toward exponential expansion. Driven by clean energy adoption, the market is poised for massive valuation gains through 2033, heavily rewarding customer-centric retail aggregators.
Market forecast from 2027 to 2033
Based on our econometric modeling, the Retail Electricity Market analysis projects the sector to surge from 2027 to 2033, reaching an astonishing $205.09 Billion by the end of the forecast period at a robust CAGR of 15.69%.
Segmentation analysis across consumer categories
The sector segments by End User into Residential, Commercial, and Industrial. Customer Types divide into Regulated and Deregulated structures, while Energy Sources contrast Conventional and Renewable paradigms. Each tier dictates unique supplier margins and regulatory compliance burdens.
Regional market analysis and geographic distribution
Geographic performance hinges heavily on regional market liberalization policies. Europe and North America lead in deregulated customer adoption, while parts of Asia-Pacific exhibit dominant state-regulated utility frameworks managed by entities like Tokyo Electric Power Company Holdings Inc.
In-depth regional review of key market territories
North American markets demonstrate strong retail competition via companies like NRG Energy Inc and Constellation Energy Resources LLC, whereas European markets experience intensive cross-border green tariff competition driven by aggressive carbon reduction directives.
Company profiles and strategic positioning
Leading utilities deploy distinct strategies; NextEra Energy and Duke Energy Corporation leverage massive asset bases, while specialized retailers focus on digital-first energy management solutions to secure high-value commercial accounts.
Porter's Five Forces competitive analysis
Buyer power is moderate to high in deregulated zones where switching providers is seamless. Supplier power remains constrained by wholesale market caps, while threat of substitutes rises with localized rooftop solar installations.
SWOT analysis of the retail power sector
Key strengths include captive recurring revenues, while weaknesses involve regulatory price intervention risks. Opportunities center on electric vehicle charging integration, against threats from wholesale generation price spikes.
Value chain analysis from generation to end-users
The value chain flows from bulk power generation and transmission down to retail supply, smart metering, and customer billing. Retailers capture value by aggregating demand and offering value-added energy management services.
Investment insights and high-potential areas
Investors should target retail brands integrating automated demand response platforms and renewable energy certification tracking. Companies with sophisticated digital customer portals show superior margin expansion potential.
Conclusion and key takeaways for stakeholders
The retail power sector is transitioning from a commodity utility service into an interactive digital energy ecosystem. Stakeholders must prioritize technological agility to capture projected multi-billion-dollar valuation growth.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining regulatory trade registry filings, primary stakeholder interviews with utility executives, and secondary macroeconomic indicators regarding industrial electricity consumption.
Scope of the report and coverage parameters
This report covers global retail electricity supply operations across residential, commercial, and industrial segments. Limitations exclude upstream wholesale transmission infrastructure build-outs not directly tied to retail tariff formation.
Recent developments, partnerships, and strategic moves
Recent industry momentum highlights major players forging partnerships with electric vehicle manufacturers and smart home tech providers to bundle retail electricity plans with domestic decarbonization hardware.